Longform’d. I prossimi dieci anni (parte 1)
 

L’attualità dei mercati giorno-per-giorno, in questa parte del 2022, è particolarmente poco interessante. Tutto si svolge come noi vi avevamo anticipato, i mercati sono (evidentemente) tutti in una posizione di allerta, come in attesa che succeda quel “qualcosa” che tutti temono e nessuno per ora nomina.

Chi vince e chi perde, in una situazione come questa?

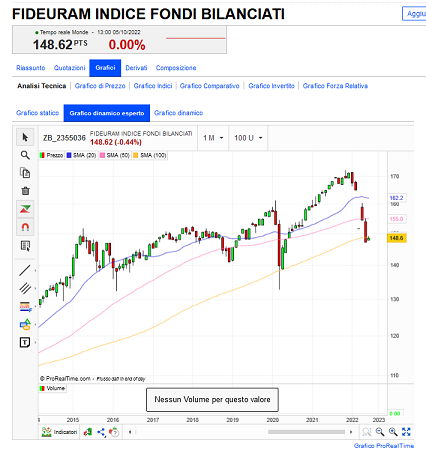
Chi perde è chiarissimo: perdono tutti quelli che si sono affidati alla cosiddetta “asset allocation” tradizionale che viene proposta (imposta) da chi vende polizze UCITS e Fondi Comuni di investimento (i numeri li trovate su tutti i quotidiani, ma pure nella pagina HOME del nostro sito, oppure nel grafico che apre questo Post, che vi racconta gli ultimi SETTE anni dei VOSTRI investimenti in Fondi Comuni, quello che si dice “un bell’affare”).

Chi vince? Chi sa fare bene il mestiere della gestione di portafoglio, sia nelle varie forme “riservate” sia nelle forme innovative, come ad esempio i portafogli modello.

Fare bene oppure fare male, in questo ambito professionale, è funzione dei risultati, pesati per il rischio. Il resto, sono solo chiacchiere.

C’è quindi un numero, molto ristretto purtroppo, di investitori che si è salvato dall’attuale disastro, grazie al fatto di avere saputo scegliere strategie di investimento ed interlocutori diversi (molto diversi) da quelli scelti dalla massa degli investitori, ed imposti da un assetto del settore del risparmio che indirizza (forzatamente) gli investitori verso soluzioni che fanno comodo solo agli Istituti che hanno ottenuto una normativa di settore che protegge gli interessi del cartello che domina il settore.

Chi oggi sta guadagnando, in qualche caso molto bene, guadagna grazie al fatto di avere anticipato i fatti che oggi tutti leggono sui quotidiani, autonomamente oppure grazie a consulenti professionali, competenti, e trasparenti (nel senso che operano senza conflitto di interesse).

Da oggi in avanti, però, che cosa sarà necessario fare, del proprio portafoglio titoli?

In questo particolare momento dei mercati, delle economie e delle società, l’investitore ha prima di tutto l’obbligo di alzare la sguardo: è infatti una gravissima ingenuità, in questo momento, perdere il proprio tempo e la propria attenzione dietro a cause perse, del tipo “quando arriva il rimbalzo”.

l contrario, è necessario alzare lo sguardo, come dicevamo: intercettare subito i cambiamenti che investono ed investiranno le Istituzioni e le società, e proprio su quella base capire (in anticipo) che cosa sta per accadere sui mercati finanziari. E quindi ai vostri e nostri soldi investiti sui mercati (ma pure nell’immobiliare: fate bene attenzione!).

Noi come sempre forniremo ai lettori un aiuto concreto, che negli ultimi anni ha dimostrato a tutto il pubblico, in forma pubblica, i suoi benefici, sia come performance sia come protezione del patrimonio dagli eventi avversi.

Tutto è, come detto, pubblico, e quindi documentato e documentabile: fate bene attenzione anche a questo aspetto, è qualificante rispetto a tutta la concorrenza delle Reti di promotori finanziari e delle banche.

Un esempio: volete rivedere quello che noi avevamo scritto più due anni fa, avvisandovi (del tutto gratuitamente) a proposito di chi era ed è anche oggi il peggiore nemico del vostro risparmio?

Vi suggeriamo, poi, di rileggere anche ciò che scrivevamo venti mesi fa.

E ciò che poi abbiamo scritto nel 2021.

Come potete facilmente riscontrare, questo è proprio ciò che oggi leggete aprendo un quotidiano: un primo esempio ve lo forniamo qui sotto, e ci è arrivato questa settimana, dal Financial Times. Altri esempi li leggerete di seguito.

A French leader once called the dollar America’s “exorbitant privilege”. Today’s world might go for blunter language. Vector of pain, anyone? Green monster? Whatever we call it, the strong dollar’s victims have one culprit in mind — the Federal Reserve. Even Josep Borrell, the EU’s foreign policy chief, is joining in.

This week he warned that the Fed was exporting recession in the same way the euro crisis was imposed by Germany’s post-2008 dictates. Much of the world is now in danger of becoming Greece. Such finger-pointing is mostly unfair to the Fed. The US central bank clung for too long to its “team transitory” dismissal of inflation and is thus tightening at speed to restore its credibility. But it is only following the rules. It is hard enough to achieve full US employment with low inflation. Adding foreigners’ wellbeing to its mandate would make the job paralysingly complex. The Fed is nevertheless the engine of global contraction. Monetary pain is America’s fastest growing export. The big unknown is, who will pick up the pieces. Here, as the world’s leading power, the US has often been prone to neglect. In today’s so-called polycrisis world it also risks missing a chance to restore America’s brand. The Fed has one tool — monetary policy. Higher US interest rates are spreading at pandemic speed.

As a whole, the US has many options. One such lever is the Bretton Woods institutions — the IMF and the World Bank, which are holding their annual meetings in Washington this week. The question is whether the US wants to cushion the blow to the developing world as its debt servicing costs go through the roof? History tells President Joe Biden which road not to take. The Fed’s last period of steep tightening started under Paul Volcker in the late 1970s. Higher US rates helped trigger far deeper recessions in the global south. Africa and Latin America both suffered a lost decade of growth that was deepened by the IMF’s punitive bailout conditions. Structural adjustment was a cure worse than the disease. The 1970s had been awash with recycled Opec capital that made dollar borrowing hard to resist. The Fed’s quantitative easing has had the same effect over the past decade. It is little consolation that inflation today looks less rampant than 40 years ago. In some respects emerging markets have it worse this time. Africa was neither responsible for the pandemic nor the war in Ukraine. The first is undoing years of human development gains. The second has unleashed a wave of food and energy inflation. Now the Fed is adding a potential debt-servicing crisis to the cocktail.

These upheavals did not originate in the global south but the costs will chiefly be borne there. That is without mentioning climate change, which is also harshest in those parts of the world least responsible for creating it. Biden has so far found little bandwidth to confront these challenges. He had a chance to make US vaccine technology available to the developing world. Indeed, he initially vowed to suspend Covid vaccine patents. That now looks like an empty gesture since his administration did not follow up. As a result, a third of the world’s population has not yet had one vaccine while most westerners have had at least two — some as many as five. Had the US taken a stronger lead, the world’s inflation-inducing supply bottlenecks would not have been as chronic.

Biden’s $1.9tn stimulus — the American Rescue Plan — threw fuel on an inflationary fire that is coming back to haunt Democrats. If they lose control of Congress next month, that bill will partly be to blame. The same applies to the roughly half a trillion dollars of student loan forgiveness he announced in August. Again, though, the brunt is felt by the rest of the world through imported austerity. The road to hell is paved with good intentions. Not for the first time, progressive-minded steps to help disadvantaged Americans are regressive for the world’s disadvantaged.

The Fed has earned some of the resentment it is getting. It should have reacted earlier to inflation, which would have meant a less punitive response. It is not as if inflation was hard to spot. On that count, Jay Powell, the Fed chair, deserves some blame. But America’s big shortcoming is political not technocratic. The global face of the problem is the mighty dollar but its causes lie deeper. The US can be oblivious at big moments to the spillover effects of what it does at home, which often come back to bite it. Call it exorbitant indifference.

edward.luce@ft.com

Non stiamo a tradurre questo articolo, e neppure i successivi: utilizzando un traduttore online, si può risolvere in pochi secondi, ma in ogni caso i contenuti possono essere intuiti da tutti. Il messaggio è chiarissimo: i quotidiani più autorevoli oggi dicono tutti: “Fight the Fed”.

Lo abbiamo scritto, in lingua italiana, nei nostri Post del 2020 e 2021 (tre link poco più in alto), che dicevano con largo anticipo proprio le stesse cose che leggete oggi, nell’articolo sopra del Financial Times qui sopra, e anche sotto nell’articolo del Wall Street Journal.

Politicians may debate whether big-government socialism or free-market capitalism leads to better economic outcomes. Their constituents may worry about rising prices and declining prospects for retirement. But neither group has the power to create money with no questions asked, manipulate the cost of capital, or counteract movements in financial markets. The central bankers are in charge—and perhaps that should change.

Even if duly elected leaders try to make good on campaign promises, they face hurdles if monetary authorities, domestic and global, disagree. What happened in Britain is a cautionary tale for nations that have relinquished to central banks the keys to economic performance. British Prime Minister Liz Truss, together with her finance minister, Kwasi Kwarteng, last month announced plans to spur investment and economic expansion by cutting taxes for individuals and businesses. Days later, they were verbally lashed by Mark Carney, a former governor of the Bank of England, for “working at some cross-purposes” with the nation’s central bank.

Mr. Carney, who is now United Nations special envoy on climate action and finance, lamented that the new U.K. government was trying to stimulate short-term growth just as the Bank of England was trying to restrain it to control inflation. While the approach championed by Ms. Truss and Mr. Kwarteng aims to expand economic output by providing incentives to increase supply, the Bank of England is committed to fighting inflation by reducing demand—which requires raising interest rates to choke off growth. When the budgetary plans were poorly received by market investors, the central bank had to buy long-term government bonds to rescue the pound in foreign-exchange markets—causing interest rates to fall.

Then there’s the audacity of the International Monetary Fund, which publicly rebuked the U.K. government’s budget and urged it to “re-evaluate the tax measures, especially those that benefit high income earners.”

Since when did unelected monetary officials gain the authority to tell political leaders what to do? It’s unseemly, but perhaps not surprising: When government organizations are imbued with breathtaking powers to determine financial conditions, it magnifies their clout—and elevates their status.

The coterie of major central banks that manage the global economy are leery of spurring demand through excessive fiscal stimulus. But there is a difference between government overspending, which borrows from the future to pay for current consumption, and tax-cutting incentives now to spur more production down the road. Government borrowing to finance socialist redistribution isn’t the same as government borrowing to invest in entrepreneurial capitalism.

But central banks, led by the U.S. Federal Reserve, have embraced the notion that curbing demand is the road to monetary redemption. That same Fed not long ago failed to anticipate the pervasive inflationary pressures unleashed through the extraordinary fiscal and monetary measures to mitigate the economic consequences of the Covid-19 shutdown.

Fed Chairman Jerome Powell insists that “price stability is the responsibility of the Federal Reserve,” but this is posturing rather than accountability. The central bank doesn’t compensate Americans for expropriating some of their wealth by diminishing the dollar’s purchasing power. And the 58% of Americans invested in the stock market won’t be comforted by former New York Fed President William Dudley’s warning this year that the Fed will “have to inflict more losses on stock and bond investors” to contract economic activity through tightened financial conditions. Citizens harmed by such moves have little recourse.

While Mr. Powell championed “supportive” monetary policy to foster economic growth and “as strong a labor market as possible for the benefit of all Americans” in announcing the Fed’s revised monetary policy framework in August 2020, he now seeks to raise interest rates to “restrictive” levels and believes “we need to have softer labor market conditions.” So much for maximizing employment.

Beyond the Fed’s dual mandate, our central bank is responsible for providing a stable monetary and financial system. But for all its powers to set interest rates, it’s not clear that supply-and-demand forces wouldn’t have set rates more appropriately and achieved better results. Is credit allocated more efficiently through central planning or free-market price signaling?

The hair-trigger reaction of financial markets to the latest utterances of monetary authorities is unsettling. Government bond yields and currency values are vulnerable to the interplay of derivative financial instruments structured on underlying assets that world-wide total about $600 trillion, according to the Switzerland-based Bank for International Settlements. Contracts based on interest rates or foreign-exchange instruments account for 96% of that total.

It is time to question whether central banks have become too powerful, too prominent and too political. In the name of preserving central bank independence, lawmakers have ceded huge swaths of their own responsibility for ensuring the welfare of citizens through sound economic policies. By doing so, elected representatives have granted influence to unelected officials that is inconsistent with democratic norms and limited powers.

It will require a Copernican revolution to shift the field of monetary theory from an understanding of economic performance that doesn’t put central banks at its core. But it’s a change that must be made if we are to prevent further demoralization of free markets and free people.

Ms. Shelton, a monetary economist, is a senior fellow at the Independent Institute and author of “Money Meltdown.”

Nell’articolo del Wall Street Journal, che nessuno al Mondo potrà accusare di essere “contrarian”, si chiede “un cambiamento del ruolo della Federal Reserve”, e si parla poi di “Rivoluzione Copernicana nella politica monetaria”.

Ai lettori, Recce’d suggerisce di NON perdere tempo con la classica domanda del private banker (“quando arriva il rimbalzo”) e concentrare invece la propria attenzione su questi due punti appena citati, e sollevati nell’articolo del WSJ.

Il Mondo, quello vero, intorno a voi viene ripensato e ridisegnato in questi mesi: quindi smettete subito, se state ancora pensando ad un futuro simile al recente passato.

Chiedetevi invece:

  1. chi ha vinto, e chi ha perso nel 2020-2022?

  2. perché pochi hanno vinto, e la massa ha perso?

  3. perché 24 mesi fa chi suggeriva “difendetevi dalla Federal Reserve” veniva etichettato come “contrarian”, ed oggi invece lo scrivono il Financial Times ed il Wall Street Journal?

Per aiutarvi a trovare le risposte giuste, potete utilizzare i tre link che vi abbiamo proposto più in alto.

E poi, potete rileggere con grande attenzione i due articoli qui sopra, ed anche il terzo articolo che trovate qui sotto di seguito, di fonte Bloomberg, dal titolo più che esplicito.

By

Bill Dudley

10 ottobre 2022 11:00 CEST

Bill Dudley, a Bloomberg Opinion columnist and senior adviser to Bloomberg Economics, is a senior research scholar at Princeton University’s Center for Economic Policy Studies. He served as president of the Federal Reserve Bank of New York from 2009 to 2018, and as vice chairman of the Federal Open Market Committee. He was previously chief U.S. economist at Goldman Sachs.

Federal Reserve officials have been getting an earful about the economic threat that the US central bank’s rapid monetary tightening presents to the rest of the world — complaints that will no doubt be amplified at this week’s meetings of the International Monetary Fund and the World Bank.

The Fed must focus on what’s best for the US, so there’s little it can do to mitigate the global repercussions of its actions. That said, it should at least do a better job of explaining itself.

The complaints are amply founded: The Fed’s aggressive monetary tightening is undoubtedly imposing stress on the rest of the world, in large part by boosting the exchange rate of the dollar to other currencies. In developed countries, this drives up prices of imports such as crude oil, stoking inflation and forcing central banks to respond with matching rate hikes — even in economies where inflation pressures are relatively mild and growth is weaker. The effects are even harsher in developing countries. Aside from more expensive food and energy imports, they face reversals of foreign capital inflows (which makes financing imports harder) and increasing difficulty servicing their already burdensome dollar-denominated debts.

Yet the Fed will almost certainly stay the course, for two reasons. First, it’s the only way to get US inflation under control. Excessive fiscal and monetary stimulus stoked the demand for goods, services and labor, so the central bank must now tighten and push up unemployment enough to slow wage and price increases. If it fails to act aggressively enough, inflation will become more embedded, forcing the Fed to act even more forcefully later with even harsher consequences for the US and global economy.

Second, the Fed’s congressional mandate is to achieve maximum sustainable employment consistent with price stability for the US economy. Congress made no mention of what’s best for the rest of the world. Of course, the Fed pays attention to global developments such as the war in Ukraine, but only to the extent that they have implications for the US economic outlook. Fed officials explain their policies to their foreign counterparts, but no adjustments are made just because the latter are unhappy. This is standard operating procedure for central banks everywhere. What’s different is how much US monetary policy affects everyone else.

Still, the Fed could do more on the communication side. Specifically, officials would do well to be more forthcoming about what went wrong, and why they now must raise short-term rates by more than 400 basis points in just nine months. A couple talking points:

  • The way the Fed implemented its new monetary policy framework, which from 2020 sought to target a longer-term average of 2% inflation, proved particularly ill-suited to the economic environment. The Fed’s self-imposed constraints were too extreme and inflexible: “Liftoff” from zero rates couldn’t happen until the economy had reached full employment and inflation had climbed above 2% and was expected to stay there for some time. Also, the Fed had to make “substantial” progress toward these goals before even beginning to taper the asset purchases known as quantitative easing, which had to be fully wound down before rate increases could begin. As a result, the federal funds rate was still at zero in early March, even though the economy had clearly overheated.

  • The Fed made two important forecasting mistakes. Inflation pressures were much broader and more persistent than anticipated, and the labor market became much tighter much faster than expected.

Humility is always valuable when you have inadvertently made life more difficult for others. Also, by recognizing its mistakes, the Fed might provide some reassurance that it won’t repeat them. It’s not much to offer countries struggling to cope with the consequences, but it’s better than the alternative of saying nothing at all.

Come avete appena letto qui sopra, adesso persino chi per un decennio è stato al governo della Federal Reserve in pubblico parla male di quello che ha fatto la Federal Reserve e dice che “la Federal Reserve deve al Mondo un mea culpa”: ma potrebbe iniziare proprio lui, Bill Dudley, Governatore della Fed di New York fino a pochi anni fa.

Peccato, per lui e per noi, che non abbia avuto la lucidità e/o il coraggio di fare considerazioni come queste quando lui era al governo di quella Istituzione.

Noi di Recce’d invece lo abbiamo fatto quando ancora era utile, e questo ha portato i nostri portafogli modello a performances eccezionali, di caratura internazionale.

Oggi però, e lo ripetiamo ancora una volta, la Federal Reserve non è più il protagonista del futuro dei mercati finanziari. Gli investitori debbono sì guardare alla Fed, ma soltanto per comprendere quali saranno le conseguenze della sua (drammatica) uscita dalla scena principale, insieme con la BCE e la Banca del Giappone.

L’investitore deve quindi, essere consapevole di ciò che accade, ma deve anche sapere anticipare i futuri protagonisti, i fattori che nel futuro prossimo e lontano daranno la direzione ai mercati finanziari.

Gli investitori, oggi, non debbono perdere tempo cn “il prossimo rimbalzo dei mercati” e devono invece occuparsi del prossimo decennio.

Noi come sempre del tutto gratuitamente attraverso questo Post mettiamo a disposizione dei lettori elementi concreti di valutazione: ad esempio con l’articolo che segue e chiude il Post.

Provate a immaginare quanti danni avreste evitato al vostro patrimonio, seguendo nel corso degli anni i nostri suggerimenti, che Recce’d vi ha offerto gratuitamente, chiedendovi di leggere con grande attenzione proprio articoli come questo.

E se oggi volete approfondire, siamo sempre stati disponibili, e lo siamo anche oggi stesso.


Rana Foroohar October 9 2022

Over 40 years ago, the Reagan-Thatcher revolution was born. Taxes were slashed. Unions were quashed. Markets were deregulated and global capital unleashed. But economic pendulums swing.

And over the last couple of weeks, it’s become quite clear that anything remotely related to trickle-down theory is now political Kryptonite. The most obvious example is, of course, the backlash against UK prime minister Liz Truss’s bizarre plan to lower taxes on the rich after announcing major spending on energy subsidies. Trussonomics is now off the table, and the prime minister’s own leadership is in jeopardy. But it’s not only the UK that is facing the downhill slope of neoliberalism. I recently met a senior Biden administration official who told me that many chief executives are now coming to Washington and asking for “a signal from government — where should we invest? Should we be in Vietnam or Mexico? Which sectors do you want us in?”

While the government isn’t yet in the business of picking winners and losers, the White House has already made the shift to a post-neoliberal era — and many in the business community are preparing for it as well. CEOs may not like the idea of a deglobalising world with more regulation, greater state control and growing labour power. But they can usually find a way to make money as long as they understand the rules of the market. So what are the new rules?

The Biden administration recently put out a clear blueprint of the economy it wants, which included five key elements. One is empowering workers, which it has endeavoured to do by using federal budgets to support unionised labour. Another is leveraging as much fiscal policy as is possible in a polarised Congress to bolster working families in areas such as healthcare and childcare, which are increasingly unaffordable for many Americans. But as commerce secretary Gina Raimondo put it to me a few months ago, government should be about more than just cutting taxes and redistributing wealth.

This administration wants to play a bigger role in directing the supply side of the private sector. In particular, it wants to encourage the making of things, not just via the push to “Buy American”, but through a more fundamental shift in policy focus from distribution to production. That means industrial policy. And while there isn’t yet a fully articulated strategy in Washington, there are clear signs that laissez-faire economics is over.

One of these is the fact that many companies will soon have to choose between the US and China. Formal decoupling between the two countries is gaining steam — there are a record number of American jobs being reshored from China, and calls for stricter rules on technology transfers. Another is that resilience and redundancy in crucial supply chains is becoming ever more important. Just a few days ago, Micron became the second big business (after Intel) to announce a major semiconductor investment in the US, putting $100bn into a new foundry in upstate New York. Federal investment in electric vehicles is also bringing new jobs to beleaguered parts of the South and Midwest. While the strong dollar may become a headwind to the administration’s hopes of growing a larger manufacturing and export economy, the lower cost of energy inputs in the US relative to Europe at the moment is a tailwind.

Support for economic “patriotism” is now the operating principle on both sides of the political divide in Washington. Robert Lighthizer, former US trade representative under Donald Trump, was famously a fan of getting rid of America’s trade deficit. But recently, Democratic California congressman Ro Khanna — a rising figure in progressive circles — called for the same thing, advocating that the US achieve a trade surplus with the rest of the world by 2035. As Khanna put it, “Trade deficits some years are fine, when balanced by trade surpluses in other years. But the country has been in constant trade deficit since 1975”. He believes that the government should help rectify this by offering zero-interest loans for factories, and increased use of federal purchasing to underwrite markets. I heard Khanna speak last week at the launch of “Reimagining the Economy”, a Harvard Kennedy School initiative led by economists Dani Rodrik and Gordon Hanson. It aims to replace neoliberal policy paradigms with something new and is one of several such programmes at major universities around the US. Many of these institutions are vying to become the epicentre of fresh economic thinking, just as the University of Chicago was the epicentre of neoliberalism. Khanna summed up the challenge of the moment: “If we can’t get the economy right, we won’t have a multiracial democracy.”

That phrasing itself represents something new — in the past, the conversations between racial equity and class inequality in the US have been separated. But Democrats are increasingly trying to link the two together, as they work to find the contours of a post-neoliberal economics. That was the topic of another big shindig last week, sponsored by the Roosevelt Institute, in which progressive politicos (many from within the administration) gathered to discuss the details of America’s industrial policy. While these aren’t completely clear yet, one thing is — all of this is the opposite of trickle-down.

rana.foroohar@ft.com

Valter Buffo
Longform'd. Il tema del giorno: "financial instability".
 

Nelle ultime settimane, due eventi (Banca di Inghilterra e Credit Suisse) hanno messo all’attenzione di operatori e commentatori il tema della “financial instability”, che era scomparso da anni.

Tutti i nostri lettori hanno notato che sui media aumenta ogni giorno il numero di riferimenti al 2007, ed alla Grande Crisi Finanziaria 2007 - 2009, ed a Lehman Brothers e Bear Sterns.

Brevemente ne parliamo in questo Post, per approfondire poi durante la settimana nel nostro quotidiano The Morning Brief, dove trovate una messa a punto quotidiana dei nostri portafogli modello (davvero indispensabile in una fase di “financial instability”).

Che cosa intendono operatori e commentatori quando usano questa espressione?

Quando si parla di “financial instability” si fa riferimento ad episodi di instabilità che si presentano, in genere in modo improvviso (per il pubblico), all’interno del settore “banche e finanza”, che include banche, non-banche che fanno credito, banche di investimento, Società di gestione dei Fondi Comuni, Fondi Hedge, e Reti di promotori finanziari, wealth managers, private bankers, robo-advisors, eccetera.

Questi episodi di instabilità ovviamente sono il riflesso di errori nella gestione delle Istituzioni che abbiamo appena elencato, errori che però vengono nascosti al pubblico per un lungo periodo (spesso con la collaborazione delle Autorità, come abbiamo visto in passato), e che spesso vengono ampliati facendo il tentativo di correggerli e salvare la baracca.

Un esempio della settimana scorsa: negli ultimi dieci anni, l’errore delle Banche centrali, che hanno schiacciato per anni il costo del denaro a zero, ha costretto i Fondi Pensione all’utilizzo degli strumenti derivati per aumentare il rendimento dei loro investimenti. I Fondi Pensione a loro volta hanno fatto alcuni errori, utilizzando in modo eccessivo i derivati.

E così siamo arrivati molto vicino ad una situazione di critica: stava per saltare in aria tutto, come ha spiegato la stessa Banca di Inghilterra giovedì 5 ottobre.

Questo fatto, e i fatti di Credit Suisse (Credit Suisse che noi commenteremo poi in una sede diversa) hanno riportato all’attenzione di tutti il concetto di “financial instability”.

In modo esplicito, in settimana ne ha parlato ad esempio Neil Kashkari.

Kashkari, come tutti ricordate, è quel membro della Federal Reserve che in data 8 aprile 2021 diceva “Se vedessi l’inflazione al 4% non ne farei un dramma” (nell’immagine che segue). Dodici mesi dopo, lui come noi ha visto l’inflazione al 9%.

Ma questo, oggi, non c’entra. Oggi ci interessa invece la frase dell’immagine qui sopra, che dice: “Mi aspetto di vedere rotture nei mercati finanziari, ma l’asticella per avere un cambiamento nella politica monetaria è posizionata molto in alto”.

Ecco spiegata la ragione immediata che rende importantissimo il dibattito sulla “financial instability”.

Il tema della “financial instability”, nell’immediato, è rilevante per i mercati finanziari e per gli investitori in ragione del fatto che potrebbe provocare un cambiamento nell’indirizzo della politica monetaria.

Lo abbiamo appena visto tutti, nel Regno Unito: la BoE è ritornata a fare QE, acquistando Titoli di Stato, a sei giorni di distanza dall’annuncio del QT, ovvero della politica di VENDITA dei Titoli di Stato già oggi nell’attivo della Banca Centrale.

Quindi: la “financial instability” può determinare un cambiamento della politica monetaria SENZA che ci siano novità sul fronte dell’inflazione, oppure dell’occupazione, oppure della crescita delle economie.

Kashkari, sopra, ha detto ai mercati: attenzione, per arrivare ad un cambiamento della politica monetaria, l’asticella sta molto in alto. Ovvero: è necessario che il problema della “stabilità finanziaria” si presenti in una forma molto grave. E’ necessaria una crisi molto grave: come fu ad esempio la crisi 2007 - 2009 di cui tanto si scrive e si parla sui media.

Anche Waller, oltre a Kashkari, ha voluto mandare ai mercati il medesimo messaggio.

Waller si è spiegato con maggiore dettaglio: ve lo documentiamo con l’immagine che segue, che però in questo Post non abbiamo lo spazio ed il tempo di approfondire.

Lo faremo in una sede diversa.

Se avete interesse a comprendere più a fondo questo aspetto dell’attualità dei mercati finanziari (aspetto che a giudizio di Recce’d oggi è decisivo per azioni, obbligazioni, materie prime e valute) ci potete contattare attraverso i canali del nostro sito.

Oppure, potete concentrarvi sulla lettura dell’articolo che abbiamo scelto per voi e che trovate qui sotto.

L’articolo di Bloomberg riassume un recente documento della Federal Reserve, articolo che spiega che esistono due diversi “tassi di interesse di equilibrio” per la Banca Centrale:

  1. uno che fa riferimento all’economia reale (inflazione, occupazione, salari, crescita del PIL, bilancia commerciale, eccetera)

  2. un secondo che fa riferimento alla “stabilità finanziaria”

L’argomento sembra molto tecnico, ma al contrario è di immediata utilità per la gestione delle vostre posizioni di portafoglio.

Questo perché, se è vero che esistono due tassi di equilibrio, allora è possibile che la Banca Centrale decida di interrompere la fase di rialzo dei tassi ufficiali, privilegiando quindi il “tasso di equilibrio per la stabilità finanziaria” rispetto al “tasso di equilibrio per l’economia reale”.

Ne riparleremo più in basso, dopo che avrete letto l’articolo che segue.

Il documento della Federal Reserve, a cui fa riferimento l’articolo che segue, è nel nostro archivio e può essere richiesto con una e-mail.

The concept of R** presented in a paper at the New York Fed last week explains the issue facing the Federal Reserve as the market desperately tries to identify the ingredients for a pivot by the central bank.

The paper lays out:

  • R* = neutral rate for the REAL ECONOMY where supply=demand and there’s no inflation, our well-known Goldilocks scenario

  • R** = neutral rate for FINANCIAL STABILITY

The authors argue that after a period of sustained low rates, similar to our current situation, the gap between R** and R* widens, with R** falling below R*. This means with excess leverage built up, the neutral rate for the financial system drops below that of the real economy.

There are parallels to today’s backdrop: real yields have begun to climb, but core PCE is still too high and the labor market is still too strong.

Yet financial stability at these rate levels is already becoming a problem: credit markets are freezing up, liquidity in Treasuries is deteriorating and dollar funding is stretched.

What does this widening gap between R* and R** mean? The financial system becomes unstable before the Fed is able to raise rates high enough to impact the labor market. In effect, the Fed will fail to rein in inflation before it’s forced to pause to tackle financial instability at home. 

This is the same situation that the Bank of England blew wide open last week with their emergency QE operation.

The next scenario for markets to grapple with: how to price a Fed that attempts to manage financial stability concerns (akin to the BOE’s liquidity operations) alongside rate hikes? Perhaps there’s another bout of risk assets plummeting and yields rising before we get to this point.

But Friday’s non-farm payrolls could be a test; a hot print could push this narrative to the next level.

Take a look at the two previous Fed hiking cycles in 2004-2006 and in 2015-2019. Back then maybe the gap between R* and R** was small, so it didn’t matter. We saw cracks in the financial system appear around the same time as the general economy. And, lets be honest, we didn’t have a real inflation fight back then, so the urgency to raise rates into restrictive territory was absent. But with this new, wider gap between the two, could financial instability take center stage before the inflation fight even truly begins?

Ora che abbiamo capito meglio che cosa è la “financial instability”, e che cosa implica per la politica delle Banche Centrali, cerchiamo di fare luce sulle ricadute per noi investitori.

Lo facciamo proponendovi in lettura un secondo articolo, che abbiamo tradotto. E’ assolutamente necessario, per tutti noi investitori, collocare nel modo corretto il fenomeno della “instabilità finanziaria” nel contesto del “cambiamento di regime” del quale questo Blog ha parlato mesi fa.

In aggunta, è necessario legare il tema della “instabilità finanziaria” al tema della “liquidità dei mercati”.

Trovate entrambe le cose proprio nell’articolo che chiude il Post.

I frequent flyer sono abituati alle turbolenze su alcuni voli. Anzi, molti se le aspettano. Tuttavia, nonostante l'attesa, ogni tanto le turbolenze possono creare ansia anche nei viaggiatori più esperti.

È quello che è successo sui mercati la scorsa settimana. Le turbolenze "attese", legate in gran parte a tre continui cambiamenti di paradigma, sono state amplificate da due fattori meno attesi, la cui durata avrà un ruolo importante nel determinare l'ordinato funzionamento dei mercati.

La maggior parte degli economisti, degli investitori e dei trader ha ormai ampiamente compreso che l'economia globale e i mercati finanziari stanno attraversando tre cambiamenti di regime:

  1. Le prevedibili iniezioni di liquidità da parte delle banche centrali e i tassi d'interesse al ribasso sono stati sostituiti da un inasprimento generalizzato della politica monetaria a livello globale.

  2. La crescita economica sta rallentando in modo significativo, poiché le tre regioni dell'economia globale più importanti dal punto di vista sistemico stanno perdendo slancio allo stesso tempo.

  3. La natura della globalizzazione si sta spostando dalla presunzione di una sempre più stretta integrazione economica e finanziaria a una maggiore frammentazione, in parte a causa delle persistenti tensioni geopolitiche.

Questi tre cambiamenti, sia da soli che collettivamente, comportano un aumento della volatilità economica e finanziaria. In termini di distribuzione dei possibili esiti economici e finanziari, lo scenario di base diventa meno attraente e più incerto, mentre aumenta la possibilità di scenari altamente negativi.

Gli sviluppi del mercato della scorsa settimana, tra cui le impressionanti oscillazioni dei prezzi del reddito fisso e dei cambi, sono andati oltre il fatto che gli investitori e i trader hanno dovuto affrontare questi tre scomodi cambiamenti di paradigma. Due ulteriori fattori hanno reso la settimana particolarmente inquietante.

Il primo è stata l'accelerazione della perdita di fiducia nei confronti della politica. I mercati, che per anni hanno apprezzato la Federal Reserve statunitense e il governo britannico come soppressori della volatilità, sono passati a considerarli come fonti significative di instabilità inquietante.

Dopo essersi lasciata sedurre dalla nozione di inflazione "transitoria" e essersi addormentata al volante della politica, la Fed sta giocando un enorme recupero per contrastare un'inflazione elevata e dannosa. Ma essendo rimasta così indietro, è ora costretta ad alzare aggressivamente i tassi in un'economia nazionale e globale in rallentamento. In questo modo, la finestra un tempo spalancata per un atterraggio morbido è stata sostituita dalla scomoda probabilità che la banca centrale faccia precipitare gli Stati Uniti in una recessione, con danni che si estendono ben oltre l'economia nazionale.

Nel Regno Unito, il nuovo governo del Primo Ministro Liz Truss ha optato non solo per le riforme strutturali e la stabilizzazione dei prezzi dell'energia, ma anche per tagli fiscali non finanziati di una portata mai vista negli ultimi 50 anni. Preoccupati dalle implicazioni per l'inflazione e il fabbisogno di prestiti, i mercati hanno fatto scendere il valore della sterlina a un livello mai visto prima nel 1985. Inoltre, hanno provocato la più grande impennata di sempre dei costi di finanziamento, misurata dal rendimento dei titoli di Stato a cinque anni.

Entrambi questi sviluppi sono intrinsecamente destabilizzanti, dal punto di vista economico e finanziario. Ed entrambi sono difficili da invertire nel breve periodo.

Il secondo fattore aggiuntivo riguarda i flussi di fondi e le implicazioni per la liquidità del mercato.

Secondo i dati compilati da Bank of America, circa 30 miliardi di dollari sono usciti dai fondi azionari e obbligazionari al dettaglio per passare alla liquidità. Questo e altri indicatori, come l'aumento record delle opzioni di protezione contro i ribassi azionari, indicano la possibilità di grandi riallocazioni di asset che hanno messo a dura prova l'ordinato funzionamento dei mercati.

Quanto maggiori sono le tensioni sul funzionamento dei mercati, tanto più i trader e gli investitori si preoccupano di non essere in grado di riposizionare i loro portafogli come desiderato. E più non riescono a fare ciò che desiderano, più aumenta il rischio di contagio. Questo vale in particolare per il reddito fisso, dove molte obbligazioni risiedono ora nei bilanci delle banche centrali.

Come illustrato nelle precedenti rubriche di Bloomberg Opinion, mi aspettavo già un aumento della volatilità e un calo dei prezzi mentre i mercati attraversavano i tre grandi cambiamenti di paradigma. Gli sviluppi della scorsa settimana evidenziano il rischio di un'ulteriore instabilità di facciata che complica un viaggio già accidentato verso nuovi equilibri economici e finanziari, rendendo più probabili gli errori di investimento comportamentali.

Mercati oggiValter Buffo
Che recessione ci attende?
 

Ricordate il “soft landing”? Ricordate il dibattito tra “soft” ed “hard” landing?

Il dibattito era al centro dell’attenzione nel primo semestre, perché fino all’estate tutte le banche di investimento sostenevano la visione delle Banche centrali, secondo la quale “ce la faremo a frenare l’inflazione senza provocare la recessione”.

Oggi, come dice El Erian nell’immagine che apre il Post, una “recessione profonda” potrebbe essere persino, per tutti quanti noi, la migliore opzione che ci è rimasta.

Ed infatti tutti hanno cambiato idea, negli ultimi mesi: tranne Recce’d che era già più avanti, e da anni. Noi eravamo “contrarian”, fino a qualche mese fa, oggi siamo diventati “il leader della maggioranza”.

Nessuno oggi utilizza più l’espressione “soft landing” e le Banche centrali, tutte, hanno già promesso al pubblico che “ci sarà da soffrire”.

Ben arrivate! Era ora!

Noi avevamo su questo argomento le idee chiarissime già nel 2021, e lo avevamo reso pubblico anche qui nel nostro Blog.

Moltissimi nostri lettori, però, si affidano ancora alle vecchie Reti di promotori finanziari, che oggi si fanno chiamare wealth managers e personal bankers, e che ai loro Clienti hanno fatto perdere parecchi soldi nel 2022 mantenendoli su posizioni totalmente sbagliate, posizioni che nel corso del tempo erano state giustificate prima con il tema della “inflazione transitoria” e poi con il tema del “soft landing”.

Per tutti questi investitori, è utile ancora oggi rivedere, e correggere, le aspettative sul futuro delle economie. Cosa che noi aiutiamo, in questo Post, selezionando e ripubblicando due articoli dedicati proprio a questo argomento.

Argomento che, come leggete qui sotto, nell’ultima settimana ha portato persino le Nazioni Unite a lanciare un allarme, accompagnato dalla richiesta, a tutte le Banche Centrali, di rallentare nella manovra di rialzo dei tassi di interesse. Ragione ulteriore per un approfondimento del nostro tema.

L’argomento è, ovviamente, di massima attualità anche per le banche di investimento: Citigroup una settimana fa ha rivisto al ribasso il proprio target per la Borsa di New York, motivando questo taglio proprio sulla base delle elevate probabilità di una severa recessione.

Nel primo dei due articoli che abbiamo selezionato per questo Post, leggerete l’intervista di Marketwatch ad un noto gestore di portafoglio, che espone una visione di quello che ci aspetta dall’economia molto vicina a quella di Recce’d.

Ritorneremo anche in altri Post, sui temi di questa intervista. in modo particolare, quando tratteremo della prossima stagione delle trimestrali delle Società quotate, e commentando la strategia di gestione dei nostri portafogli modello.

Keith McCullough, founder and CEO of Hedgeye Risk Management, isn’t one to mince words about financial markets, the Federal Reserve or the economy.

Right now he has a few less-than-charitable things to say about how the Fed’s rate hikes have ground up stock and bond investors.

His investment-research firm’s economic models turned bearish on stocks and bonds at the beginning of 2022. Prices have since tumbled, but McCullough is still bearish. He’s now steering investors to defensive positions primarily in cash, the U.S. dollar, gold and income-producing equities.

McCullough is preparing investors for the painful recession he expects for both Wall Street and Main Street in 2023. To anyone expecting the Fed to realize its rate increases have been excessive and rescue the markets, McCullough is blunt: “There’s no dovish pivot,” he says.

Even if the Fed were to relent, McCullough says the damage is done. “They’re far too late,” he says of the Fed. “Just like it was impossible for them to stop inflation, it’s impossible for them to stop the pending U.S. corporate profit recession or the mainline recession.”

In this recent interview, which has been edited for length and clarity, McCullough outlines his base case for the U.S. economy and the financial markets going into 2023, and advises investors to take shelter from a coming storm many of them have never seen.

‘The recessionary economic data keeps getting worse.’

MarketWatch: In a MarketWatch interview last April, you said “the Fed always screws up” and predicted a bear market for U.S. stocks in the summer. That happened. What do you expect now from the Fed — learn from its mistakes or make more?

McCullough: Recession today is what “transitory” inflation was a year ago. The Fed is as wrong on recession risk as they were on inflation.

I’m about as bearish as I’ve been since 2008. Instead of the economy having a soft landing, I think the landing is going to be hard. The recessionary economic data keeps getting worse, not just in the U.S. but in Europe as well.

Free money forever created behavioral problems and a behavioral bubble for the markets and investors. You believe you’ll have unlimited access to easy money and your behavior, whether you’re building profitless growth companies through storytelling or cryptocurrencies that also are just stories. You’re coming from the mother of all behavioral bubbles that now will be addressed with tighter money. When you’re printing money and the economy is accelerating to the fastest growth rate ever, you’re going to have the mother of all bubbles. Now, GDP is going to slow to zero, and you get the opposite.

MarketWatch: A hard landing for the economy and an economic environment echoing the 2008 financial crisis is a pretty damning verdict. You’re not in the perma-bear camp with some forecasters, so what are you seeing now to have such a pessimistic outlook?

McCullough: On a lot of levels it’s worse now than in 2008. If 2008 was about Wall Street collapsing on itself, on all its conflicts of interests and lies, this one is more about Main Street. Main Street is broke. Main Street is taking all this inflation into their cost of living. Main Street has the highest credit-card interest going back to the 1990s. It’s way worse than 2008 on that basis. If you’re trying to pay your bills with credit, it’s getting worse and worse. And then they’re going to lose their jobs. Labor collapsing is always the last thing to go down. We’re right on the cusp of the labor cycle going the wrong way.

That’s what’s going on right now. GDP and profit growth are both going negative. The Fed is going to see all of that and have to change. The big screw-up people will have is that the minute they see Fed dovishness, they’re going to buy stocks and crypto. Then they’re going to realize they’re in a recession, which is an entirely different setup from what got those bubbles to begin with, which was unlimited easing and fiscal support plus GDP growth.

We have economic deceleration irrespective of what the Fed does. It’s impossible for the Federal Reserve to stop gravity. They’re far too late. Just like it was impossible for them to stop inflation, it’s impossible for them to stop the pending U.S. corporate profit recession or the mainline recession.

MarketWatch: It isn’t just the Fed that could miss the recession signs until it’s too late. Stock investors as well might find themselves on the wrong side of the tracks.

McCullough: The Fed first has to realize that what I’m talking about is the high-probability event. That will take time. It’s not going to take them a month. They have to realize we’re in a recession, then make the commensurate policy pivot. Then, when the Fed does go dovish and realize we’re in a recession, that’s bad for the stock market.

The Pavlovian response is the Fed is dovish, buy stocks. That’s true if you’re not in a recession. This next recession — which could be the biggest profits recession of the modern era — will be quite an education for people who are still bullish, with the expectation that the Fed is going to save them.

MarketWatch: Many Fed-watchers and market analysts expect the Fed to pause or slow rate hikes to assess the effects of their inflation-fighting efforts. Do you see a “Powell pivot” coming?

McCullough: There’s no dovish pivot. The level of inflation is nowhere near the Fed’s target. And there’s a midterm election coming up. They’ve already established that the rate hikes are going to go right up to November. Rate hikes are baked into the cake and anybody looking for it to turn into a birthday cake for the bulls will be sadly disappointed.

An entire generation of Americans hasn’t gone through a recession. A lot of companies in Silicon Valley have never been through a recession, for example. My definition of a U.S. corporate profits recession is when the rate of change of revenue growth has gone negative and the rate of change of year-over-year profit growth has gone negative. The Federal Reserve, even if it were to turn dovish on interest rates tomorrow, will have a hard time stopping the profits recession.

When the rate of economic change is accelerating and the Fed is printing money, you buy anything that’s got a good chart and a good story. You’re going to make a lot of money until the music stops.

And it did. Now we’re seeing the opposite. The rate of change of real GDP growth and inflation are slowing at the same time. You can’t own inflation, commodities or growth now. If you’re still long pretend growth or profitless growth or crypto, I recommend prayer.

MarketWatch: Given the grim picture you’ve drawn, where are you directing investors to put their money to weather the storm?

McCullough: There aren’t many places to hide. Our biggest position in equities is utilities.Utilities is a bond proxy. We still like gold .

If you have to own stocks, we like quality balance sheets, profitable companies that have high-quality cash-flow streams. We’re short growth — all of it. We’re short all of tech. Energy stocks are levered up on the long side. I’ll take my time on that. It is a place I’m interested in buying, but currently we’re only long natural gas and solar through the Invesco Solar ETF We’re bearish on oil , copper — every major commodity other than natural gas. We’re short Europe on the equity side and on the euro . I’m in no rush to cover those shorts. The trend is down for stocks and up for the U.S. dollar .

Also Treasury bonds, but you have to wait, watch and act as the game plays out. If the U.S. 10-year Treasury breaks down below 2.95% that’s a pretty obvious green light to make long-term Treasurys one of your top asset allocations. A lot of people are trying to pick bottoms in stocks. I’m much more interested in buying Treasury bonds than anything else.

A questa utile intervista aggiungiamo le considerazioni più recenti di Nouriel Roubini, che non a caso dai media è stato etichettato come “profeta di sventura”. Come abbiamo già scritto, la nostra visione delle cose è spesso distante da quella di Roubini: in questa specifica occasione però, a nostro giudizio, è particolarmente utile leggere i sui argomenti, tanto quanto fu utile negli anni 2006 e 2007.

Come sempre nelle sue analisi, Roubini mette insieme moltissime cose, argomenti di finanza, di economia, di sociologia, insieme con argomenti che riguardano la politica, l’ambiente, ed altro.

Una lettura attenta vi permetterà, comunque, di cogliere spunti importanti, come ad esempio quello della “fiscal capture” che si lega in modo stretto al tema della “financial instability” (al quale Recce’d oggi dedica un altro Post).

Vi segnaliamo poi il riferimento al portafoglio 60/40, che le nostre Reti di promotori finanziari e private bankers chiamano “portafoglio bilanciato ad asset allocation”, del quale Recce’d ha scritto e scriverà nella pagina SCELTE DI PORTAFOGLIO.

NEW YORK (Project Syndicate)—For a year now, I have argued that the increase in inflation would be persistent, that its causes include not only bad policies but also negative supply shocks, and that central banks’ attempt to fight it would cause a hard economic landing.

When the recession comes, I warned, it will be severe and protracted, with widespread financial distress and debt crises. Notwithstanding their hawkish talk, central bankers, caught in a debt trap, may still wimp out and settle for above-target inflation. Any portfolio of risky equities and less risky fixed-income bonds will lose money on the bonds, owing to higher inflation and inflation expectations.

How do these predictions stack up? First, Team Transitory clearly lost to Team Persistent in the inflation debate. On top of excessively loose monetary, fiscal, and credit policies, negative supply shocks caused price growth to surge. COVID-19 lockdowns led to supply bottlenecks, including for labor. China’s “zero-COVID” policy created even more problems for global supply chains. Russia’s invasion of Ukraine sent shock waves through energy and other commodity markets.

Central banks, regardless of their tough talk, will feel immense pressure to reverse their tightening once the scenario of a hard economic landing and a financial crash materializes.

And the broader sanctions regime—not least the weaponization of the dollar and other currencies—has further balkanized the global economy, with “friend-shoring” and trade and immigration restrictions accelerating the trend toward deglobalization.

Everyone now recognizes that these persistent negative supply shocks have contributed to inflation, and the European Central Bank, the Bank of England, and the Federal Reserve have begun to acknowledge that a soft landing will be exceedingly difficult to pull off. Fed Chair Jerome Powell now speaks of a “softish landing” with at least “some pain.” Meanwhile, a hard-landing scenario is becoming the consensus among market analysts, economists, and investors.

It is much harder to achieve a soft landing under conditions of stagflationary negative supply shocks than it is when the economy is overheating because of excessive demand. Since World War II, there has never been a case where the Fed achieved a soft landing with inflation above 5% (it is currently above 8%) and unemployment below 5% (it is currently 3.7%).

And if a hard landing is the baseline for the United States, it is even more likely in Europe, owing to the Russian energy shock, China’s slowdown, and the ECB falling even further behind the curve relative to the Fed.

The recession will be severe and protracted

Are we already in a recession? Not yet, but the U.S. did report negative growth in the first half of the year, and most forward-looking indicators of economic activity in advanced economies point to a sharp slowdown that will grow even worse with monetary-policy tightening. A hard landing by year’s end should be regarded as the baseline scenario.

While many other analysts now agree, they seem to think that the coming recession will be short and shallow, whereas I have cautioned against such relative optimism, stressing the risk of a severe and protracted stagflationary debt crisis. And now, the latest distress in financial markets—including bond and credit markets—has reinforced my view that central banks’ efforts to bring inflation back down to target will cause both an economic and a financial crash.

I have also long argued that central banks, regardless of their tough talk, will feel immense pressure to reverse their tightening once the scenario of a hard economic landing and a financial crash materializes. Early signs of wimping out are already discernible in the United Kingdom. Faced with the market reaction to the new government’s reckless fiscal stimulus, the BOE has launched an emergency quantitative-easing (QE) program to buy up government bonds (the yields on which have spiked).

Monetary policy is increasingly subject to fiscal capture. Recall that a similar turnaround occurred in the first quarter of 2019, when the Fed stopped its quantitative-tightening (QT) program and started pursuing a mix of backdoor QE and policy-rate cuts—after previously signaling continued rate hikes and QT—at the first sign of mild financial pressures and a growth slowdown.

The Great Stagflation

Central banks will talk tough; but there is good reason to doubt their willingness to do “whatever it takes” to return inflation to its target rate in a world of excessive debt with risks of an economic and financial crash.

Moreover, there are early signs that the Great Moderation has given way to the Great Stagflation, which will be characterized by instability and a confluence of slow-motion negative supply shocks.

In addition to the disruptions mentioned above, these shocks could include societal aging in many key economies (a problem made worse by immigration restrictions); Sino-American decoupling; a “geopolitical depression” and breakdown of multilateralism; new variants of COVID-19 and new outbreaks, such as monkeypox; the increasingly damaging consequences of climate change; cyberwarfare; and fiscal policies to boost wages and workers’ power.

Where does that leave the traditional 60/40 portfolio? I previously argued that the negative correlation between bond and equity prices would break down as inflation rises, and indeed it has. Between January and June of this year, U.S. (and global) equity indexes fell by over 20% while long-term bond yields rose from 1.5% to 3.5%, leading to massive losses on both equities and bonds (positive price correlation).

Moreover, bond yields fell during the market rally between July and mid-August (which I correctly predicted would be a dead-cat bounce), thus maintaining the positive price correlation; and since mid-August, equities have continued their sharp fall while bond yields have gone much higher. As higher inflation has led to tighter monetary policy, a balanced bear market for both equities and bonds has emerged.

But U.S. and global equities have not yet fully priced in even a mild and short hard landing. Equities will fall by about 30% in a mild recession, and by 40% or more in the severe stagflationary debt crisis that I have predicted for the global economy. Signs of strain in debt markets are mounting: sovereign spreads and long-term bond rates are rising, and high-yield spreads are increasing sharply; leveraged-loan and collateralized-loan-obligation markets are shutting down; highly indebted firms, shadow banks, households, governments, and countries are entering debt distress.

The crisis is here.


Nouriel Roubini, professor emeritus of economics at New York University’s Stern School of Business, is chief economist at Atlas Capital Team and author of the forthcoming “MegaThreats: Ten Dangerous Trends That Imperil Our Future, and How to Survive Them” (Little, Brown and Company, October 2022).

Valter Buffo
Pivot/Godot
 

Commentare di settimana in settimana gli alti e bassi degli indici è nella maggior parte dei casi tempo sprecato inutilmente.

Nel 2022, poi, commentare gli alti e bassi di Borsa di breve periodo è tempo sprecato nel 100% dei casi.

Se ci fermiamo, con questo Post, a commentare l’ultima settimana delle Borse, è unicamente per la ragione che dall’ultima settimana è possibile ricavare insegnamenti ed indicazioni di carattere generale.

Nell’ultima settimana, è tornato a circolare tra gli operatori il termine “pivot”: a questo scopo, le Reti di promotori finanziari e le banche globali di investimento hanno del tutto INVENTATO una previsione per il dato del 7 ottobre che avrebbe dovuto fare segnare un CALO degli occupati.

Per un sintetico commento prendiamo a prestito le parole di Mohamed El Erian che leggete sopra nell’immagine:

La visione di “picco” di tutto (picco del petrolio, picco dei tassi, picco del dollaro) è stata nuovamente messa in discussione dai mercati finanziari negli ultimi giorni.

La visione del “picco di tutto” aveva contribuito nei giorni a fare rinascere il sogno romantico dei mercati per il “pivot”.

Le parole di El Erian sono efficaci ed esaustive. Un investitore però deve domandarsi: perché questa storia del “pivot” ritorna regolarmente, anche se ogni volta poi viene (pesantemente) smentita?

Proviamo a ragionare di questo.

Nella seconda immagine qui sopra, è sempre El Erian che scrive, a proposito del “sogno romantico del pivot” che necessità di maggiore supporto fondamentale. Aggiungendo poi che:

Convincersi delle cose senza avere il supporto dei fondamentali non è un buon modo di investire.

Ecco quindi svelato, da El Erian, il mistero del “pivot”: che torna, e ritorna, e ritorna ancora, ad opera di soggetti (individui ed Istituzioni) che intenzionalmente lavorano per distrarre l’attenzione degli investitori dai dati fondamentali.

Questo è lo scopo del “pivot”: spingere gli investitori finali a spostarsi verso asset ed asset class che oggi NON hanno alcun supporto dai fondamentali.

Per ottenere questo risultato (almeno con una parte degli investitori) è necessario lavorare di fantasia, e nascondere la realtà.

Ecco spiegato perché “i mercato finanziari si muovono sulla base di narrative”, come dice proprio all’esordio l’interessante articolo che segue.

Articolo che ci serve per ricostruire la recente esperienza con il “pivot”, e che ci ha pure suggerito il titolo del Post: “Aspettando Godot”.

La lettura di questo articolo vi aiuta a realizzare quanto segue: la rappresentazione di un futuro in cui l’economia rallenta ma non troppo, mentre l’inflazione è un problema che si risolve da solo senza sforzo, è nulla di più di una favoletta da raccontare ai bambini, costruita ed utilizzata per “piazzare la merce” da parte delle Reti di vendita dei Fondi Comuni insieme con le banche globali di investimento.

Una favola: una cosa che NON esiste.


Financial markets trade on narratives. And for the past several weeks, the dominant story in both bond and equity markets has been that the Fed will pivot, and soon. Investors expect a rapidly weakening economy to force the US central bank to do an about-turn, and cut rates barely months after hikes finish.

This belief built up a head of steam across July, with many investors suggesting that the Fed could signal a shift at its Jackson Hole retreat in late August. Every weak housing data point fed into this narrative; every contraction in PMI was grist for this mill. A sharp pullback in commodities prices, a collapse in business and consumer confidence, a decline in market expectations for inflation over the next decade – all these pointed in that same direction.

And then there was history: the Fed did a volte-face in both of the last two hiking cycles. Hikes in the summer of 2007 gave way to cuts in 2008. And memorably, the Fed hiked in December 2018 only to change course by January 2019. Small wonder that markets have been waiting for the US central bank to signal a shift again.

Easier said than done. The data that matter most – inflation and wages – are still too strong for the US central bank to breathe easy. Way too strong. And the numbers are accelerating, even before July’s strong jobs report.

Consider the last inflation print. Core CPI (which excludes food and energy prices) over 6 months is running at an annualised pace of almost 7 per cent. But the 3-month rate is almost 8 per cent. And the 1-month number annualised is nearly 9 per cent. That means core CPI is speeding up, not slowing down, and is in a very different zip code than the Fed’s 2-per-cent target.

Even more important is the move in wages. For the past few months, it looked like wage growth was slowing down. Average hourly earnings, reported in the monthly jobs report, seemed to have settled into a 3.5- to 4-per-cent annual rate.

Then three things happened all at once.

  • First, the Atlanta Fed wage growth tracker showed that wages accelerated strongly in June (6.7 per cent annually):

  • Second, the average hourly earnings data were revised upwards. Lo and behold, wages are no longer slowing in that series.

  • But most significant was the latest release of the Employment Cost Index (ECI), the Fed’s preferred indicator. Private sector wages accelerated sharply to a 6.5-per-cent annualised pace in June.

The cherry on the cake, of course, was the unemployment rate reaching a post-Covid low last week. The US labour market is not just not slowing down. It is speeding up. It is true that labour markets are famously backward looking.

In September 2008, around the financial crisis, the jobless rate was still 6.1 per cent. When it peaked at 9.9 per cent a year and a half later, the US was well on its way to recovery. Even so, Fed officials care deeply about wages. If high wage expectations get embedded in an economy, high inflation can remain ‘sticky’ for far longer. A 2-per-cent inflation target is hard to achieve if per-capita wages rise 6 per cent in 2023.

Central bankers don’t like admitting it, but a primary goal of rate hikes is to cause enough job losses to ensure that wage growth slows down. And if that isn’t happening despite several rate increases, it adds pressure on the central bank to raise rates further, and keep them high for longer. Admittedly, monetary policy does work with a long and variable lag.

That is why central bank decisions are usually based on forecasts; today’s data is not supposed to be the dominant driver of today’s policy. But these are not normal times. The inflation spike of the last 12-15 months has been massive, persistent, and made a mockery of forecasts. And one by one, central banks have had to adjust policy to incoming inflation data.

The Fed broke its own forward guidance and hiked 75bp in June because of a strong May CPI report. And the ECB followed in July, hiking 50bp despite promising 25bp. Strong jobs reports are usually greeted with enthusiasm in the Marriner S Eccles building. But the starting point on inflation, including core inflation, is simply too high. Markets have gotten ahead of themselves in expecting the Fed to start taking a more dovish approach.

As things currently stand, any Fed surprises over the next few months are more likely to be hawkish. Investors waiting for an imminent pivot will have to keep waiting.

Valter Buffo
Tonnara (parte 2)
 

Nel Post con il medesimo titolo che abbiamo pubblicato nel weekend 1 - 2 ottobre, si discuteva di pubblicità TV e sui media.

Recce’d ha messo in evidenza le tante pubblicità il cui messaggio principale è che investire sui mercati finanziari è facile, che “basta un attimo”, e che lo si può fare mentre si gioca con lo smartphone, proprio come per gli altri canali social (ad esempio Tik Tok, Instagram e Twitter)

Magari, mentre si guarda il “Grande Fratello VIP”, si può dare uno sguardo al prezzo del petrolio oppure del titolo Tesla.

Tanto, sale sempre tutto.

In quel nostro Post del weekend, si citava, come esempio di una certa “cultura dell’investimento”, Dave “The Trader” Portnoy, personaggio popolarissimo sui social e pure sui media tradizionali solo un anno fa, ed oggi messo del tutto da parte sia dai social sia dai media tradizionali, che nel 2022 non lo intervistano più. Chissà perché.

Noi allora, per bilanciare le cose, abbiamo trovato un video di Dave che ci è parso interessante, e ben costruito. E lo proponiamo ai lettori.

Vi sarà sufficiente fare click sull’immagine qui sotto, per vederlo.

Fate massima attenzione, in basso, allo scorrere delle date. Tutta la magia di questo video sta lì, nelle date.

E non dimenticate che, come spiega un famoso spot TV “per investire basta un attimo”.

Valter Buffo